ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Austell
Dump trucks take a beating: loaded beds, rough job sites, rock chips and tight backing. We help you put coverage in place that fits your trucks and your contracts, and we walk you through documenting damage if something goes wrong.
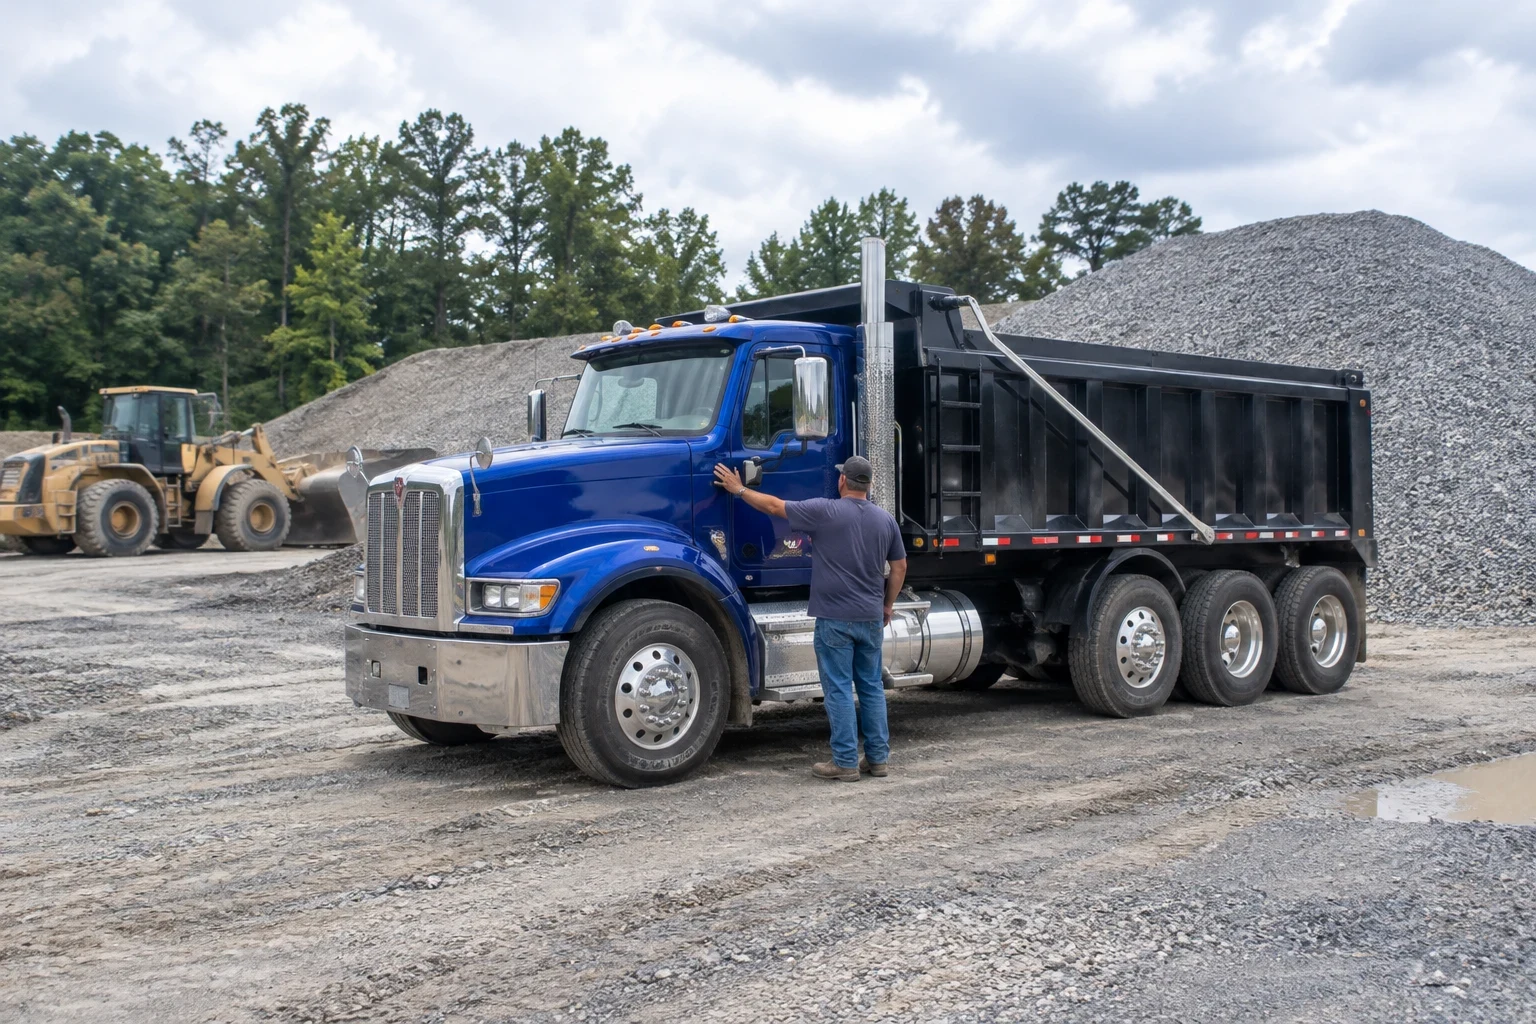
Coverage built for trucks that work off the pavement
A tri-axle hauling gravel to a grading site faces different risks than a tractor running freight on the interstate. Your truck sits on soft ground, raises a loaded bed, backs around crews and equipment, and kicks up rock that cracks windshields, yours and other people's. Your policy should reflect that work, not a generic trucking form.
We're licensed for property and casualty insurance, and we set up dump truck and construction truck policies for owner-operators and small fleets running end dumps, side dumps, tri-axles, quad-axles and other job-site units. We explain what each part of the policy does, where the gaps usually show up, and what a general contractor will expect to see on your certificate of insurance.
We also stay with you after the policy is written. If a truck is damaged or there's an incident on a job, we help you gather the right photos and paperwork and explain how the claim moves forward. The carrier's adjuster makes the final call on what gets paid, and we tell you that up front.
What a dump truck policy usually covers
Primary auto liability
Covers injury and property damage you cause to others while operating. It's the core of the policy and the piece most contracts set minimum limits for. Our Primary Auto Liability Insurance page goes deeper.
Physical damage for your truck
Collision and comprehensive coverage for the truck itself, set at a value that matches what it would cost to replace. We look closely at how upset and rollover are handled, since a bed raised on uneven ground is a real risk. See Physical Damage Insurance for more.
Certificates for contractors
Job-site work almost always means a certificate of insurance, often with the contractor listed by name through an endorsement. We help you get certificates issued the way each contract asks, so you aren't held off a job over paperwork.
Filings when you need them
Depending on truck weight and whether you cross state lines, you may need a DOT number and state or federal filings. We check what applies to your operation and make sure the filings match the policy.
Cargo coverage, if a contract calls for it
Many aggregate haulers don't carry cargo coverage, but some shippers and contracts require it. We'll tell you honestly whether it's worth adding. Motor Truck Cargo Insurance has the details.
Signs it's time to review your dump truck coverage
A contractor rejected your certificate
If a general contractor sent back your certificate for low limits or missing endorsements, your policy may not match the work you're bidding.
You added a truck or a driver
A new unit or a newer driver changes your risk and your premium. Waiting until renewal to report it can leave a gap if something happens in between.
Your truck's value has changed
If you upgraded the bed, added equipment or bought a newer truck, an old stated value could leave you short after a total loss.
You're running farther than you used to
Hauling beyond your usual local radius or across state lines can change your filings and your rating. Your policy should reflect where you actually run.
You aren't sure what's covered on the job site
Damage while dumping, a rock through someone's windshield, a backing incident near a crew. If you can't say how your policy treats each one, it's worth a call.
How getting covered works with us
- 1
A conversation by phone or video
We ask about your trucks, what you haul, your typical radius, your drivers and any contracts you're working under. You can also stop by our office in Austell if you'd rather sit down in person.
- 2
We shop and compare
We bring your details to carriers that write construction and dump truck risks, then lay the options side by side. You see the limits, deductibles and exclusions, not just the premium.
- 3
Policy, filings and certificates
Once you choose, we bind coverage, handle any required filings and get your certificates of insurance issued for the contractors you work with.
- 4
Help when there's a claim
If a truck is damaged or someone files against you, we walk you through what to photograph, which records to keep and what the carrier will ask for. Good documentation early keeps things from stalling.
What shapes your dump truck premium
There's no single rate for dump truck insurance. Carriers price each operation on its own mix of trucks, drivers and work. We explain which factors are driving your quote so you know where you have room to adjust.
- Radius and routes
- A truck staying close to Austell, Marietta and Douglasville is rated differently than one running long hauls or out of state.
- Driver records and experience
- Clean motor vehicle records and years of CDL experience on similar equipment help your premium more than almost anything else.
- Truck value and type
- A newer quad-axle costs more to insure for physical damage than an older single-axle. The value you set also affects what you'd recover after a loss.
- What you haul and where
- Asphalt, demolition debris and quarry work each carry their own risk profile, and so do the job sites you work on.
- Claims history
- Past losses follow you for several years. A clean record, or a clear explanation of what happened, makes a real difference with underwriters.
Dump truck insurance questions
Something not covered here? (770) 405-1970
Do I need cargo coverage to haul gravel and dirt?
Often not, because aggregate has low value and is rarely the subject of a loss. Some contracts still require it, though. We'll read what your customers ask for and tell you whether adding it makes sense.
Is it covered if my truck tips over while dumping?
That usually falls under the collision part of physical damage coverage, but wording varies by carrier. We go over how your policy treats upset and rollover before you buy, so it isn't a surprise later.
What about rocks from my load cracking someone's windshield?
Damage to another vehicle is generally handled under your auto liability, not your physical damage coverage. Incidents like this can add up over time, so keeping your load tarped and writing down what happened each time helps.
Can you list a contractor on my certificate the way their contract asks?
Yes, in most cases we can request the endorsement the contract calls for and have a certificate issued showing it. Some carriers charge for certain endorsements, and we'll tell you if yours does before anything is added.
Will you handle my claim for me?
We help you document the damage, report it correctly and understand each step. The carrier's adjuster reviews the file and decides what's paid. We stay in touch and help you answer their questions along the way.
Let's look at what your trucks actually need
Tell us about your trucks, your drivers and the work you're bidding. We'll explain your options in plain terms and get your quote by phone.