Trucking Insurance in Austell for Owner-Operators and Fleets
We set up primary auto liability, physical damage, cargo coverage and bobtail policies for owner-operators, new motor carriers and small fleets. When something goes wrong on a load, we help you document the damage and understand each step of the claim. We work with truckers from Austell to Douglasville and Powder Springs.
- Help with your filings
- Plain-language policy reviews
- Damage documentation guidance
- Office, phone or video
Coverage Built Around Your Trucks
We are licensed for property and casualty insurance, and trucking is the work we focus on. That covers everything from commercial trucking insurance and primary auto liability to motor truck cargo, trailer interchange and non-trucking liability. We also write policies shaped for the way you run: owner-operator, new authority, fleet, hotshot, box truck, and dump or construction trucks. Pick the page closest to your operation, or call and we will sort out what applies.
Commercial Trucking Insurance
Liability, physical damage and cargo coverage matched to your freight, plus help documenting a loss and understanding what the insurance company needs next.
Primary Auto Liability
The coverage FMCSA requires before your MC authority goes active, set at limits your brokers accept, with your filings and certificates handled.
Physical Damage Insurance
Collision and comprehensive coverage for your trucks and trailers, with plain guidance on stated value, deductibles and documenting damage after a loss.
Motor Truck Cargo Insurance
Cargo coverage for the freight in your care, with commodity lists, limits and exclusions explained before a broker or shipper ever asks.
Bobtail Insurance
Liability coverage for leased owner-operators when the truck is off dispatch, matched to what your carrier's lease agreement asks for.
Trailer Interchange Insurance
Physical damage coverage for trailers and chassis you pull under a written interchange agreement, set at the limit the agreement asks for.
Owner-Operator Insurance
Coverage for drivers who own their truck, whether you run under your own MC authority or lease onto a carrier, with plain answers about how claims work.
New Authority Truck Insurance
Coverage and FMCSA filings for carriers with a fresh MC authority, set up so your authority can activate and brokers will load you.
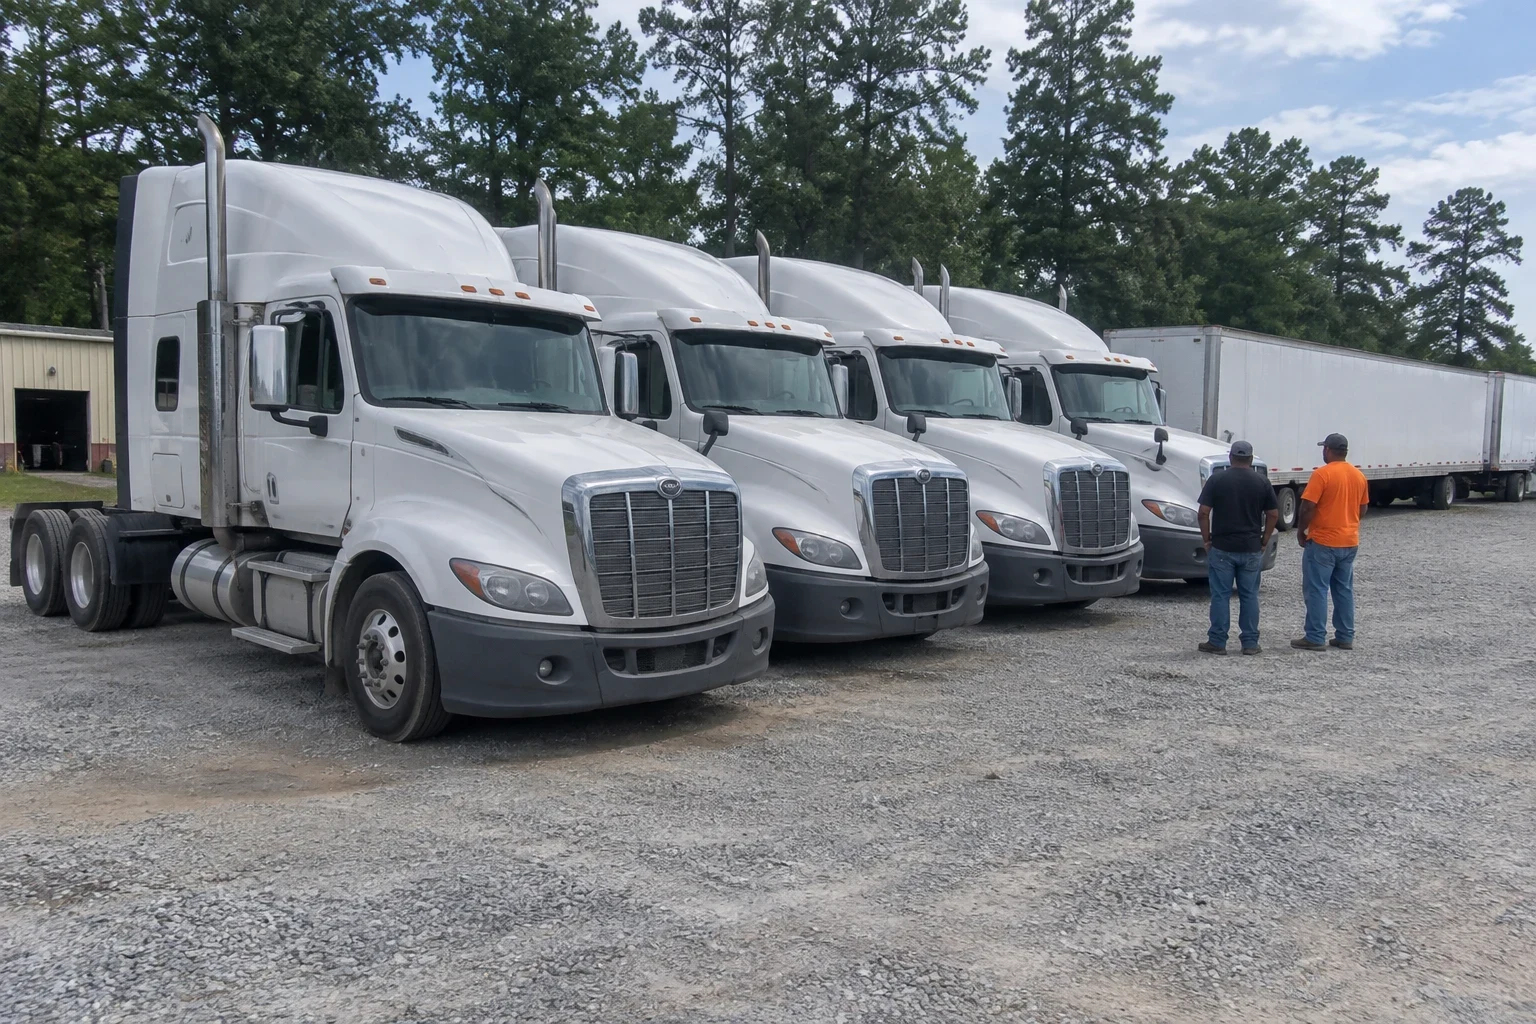
Fleet Truck Insurance
One policy for several power units and drivers, with a clean vehicle schedule, prompt certificates and steady help when a truck is damaged.
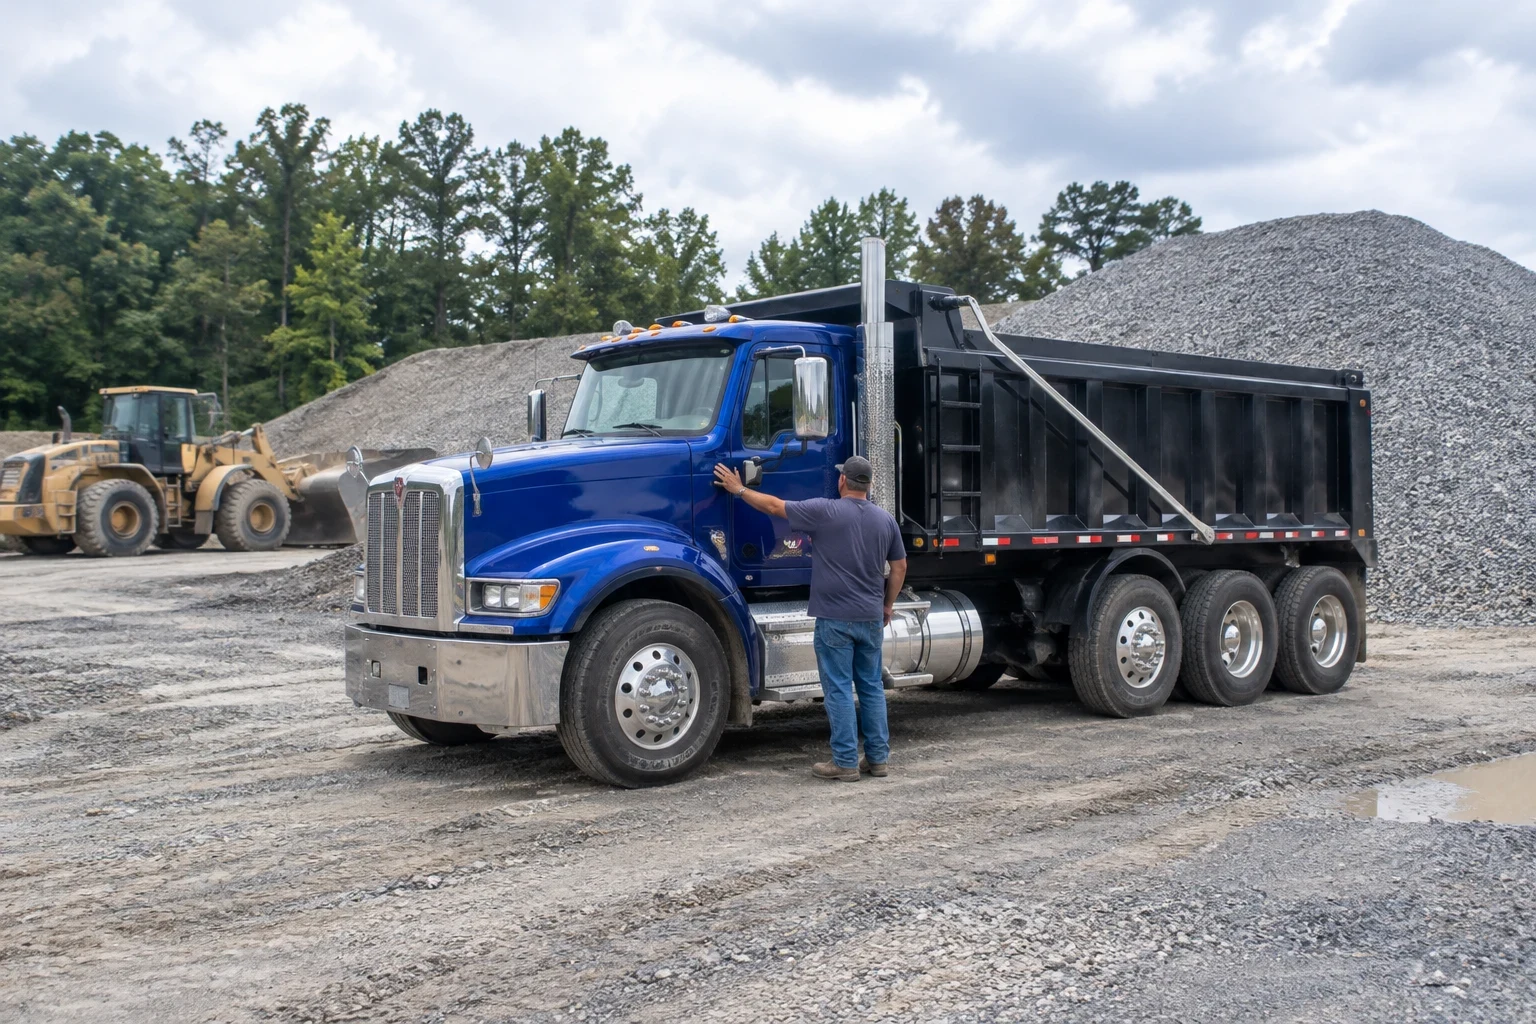
Dump Truck Insurance
Coverage for dump trucks and job-site haulers, built around what you haul, how far you run and what your contracts ask for.
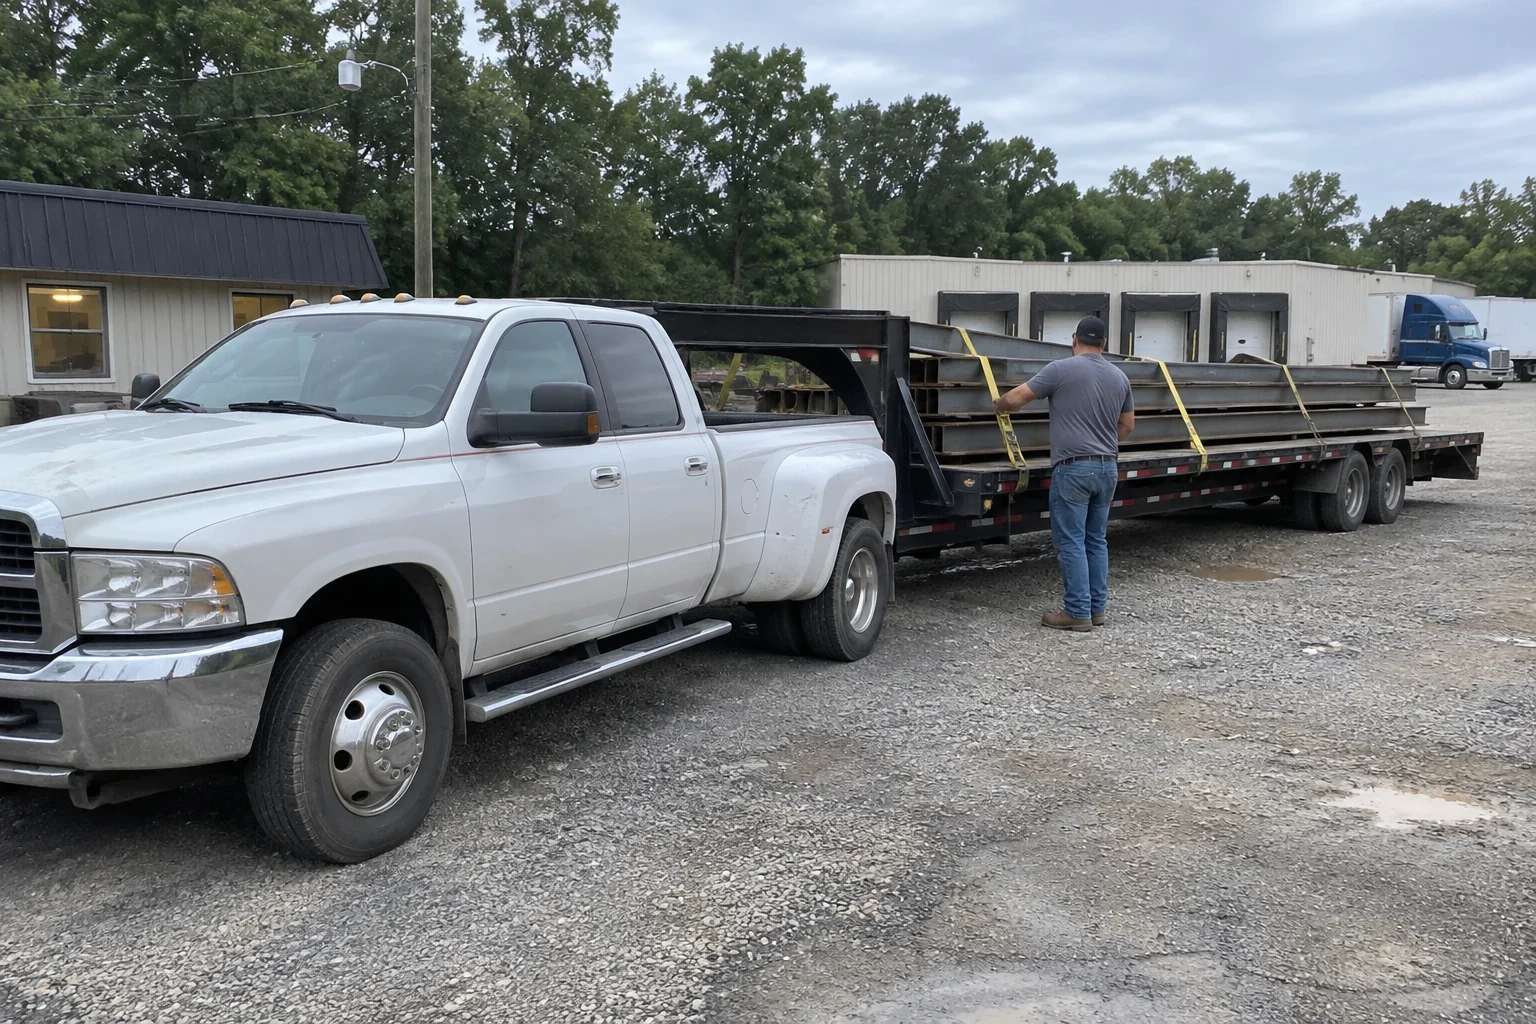
Hotshot Truck Insurance
Liability, cargo and physical damage for one-ton pickups and flatbed trailers, plus help documenting a loss when a load goes wrong.
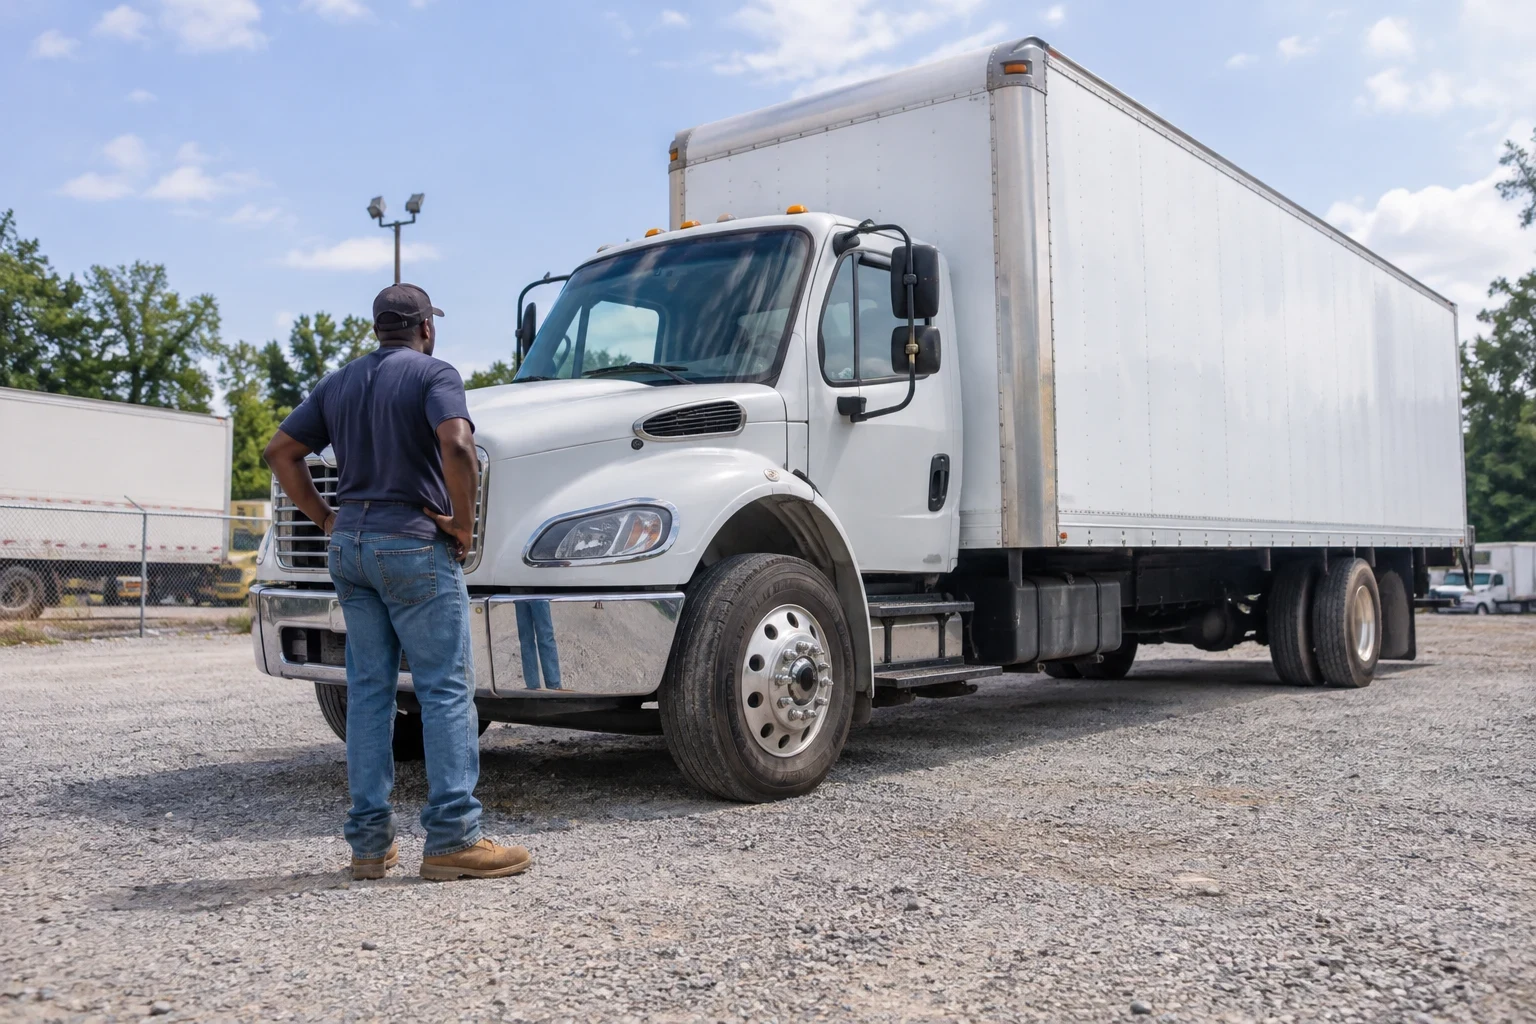
Box Truck Insurance
Liability, physical damage and cargo coverage for straight trucks and box vans, set up to match how you run and what brokers ask for.
Where We Work
Our office is in Austell, GA, and we work with truckers across the west metro. That includes carriers based in Mableton, Powder Springs, Lithia Springs, Smyrna and Douglasville. We also help operators in Fair Oaks, Hiram, South Fulton, Marietta and Dallas.
- Austell
- Mableton
- Powder Springs
- Lithia Springs
- Smyrna
- Douglasville
- Fair Oaks
- Hiram
- South Fulton
- Marietta
- Dallas
Because we meet by phone and video too, distance rarely matters. If your trucks are garaged nearby, we are glad to help.
About Trucking Insurance Austell
We are a local agency that works with the people who keep freight moving: owner-operators, new carriers, small fleets and the crews running dump, hotshot and box trucks. Our job is to get you the right coverage and make sure you understand it.
The days after a wreck or a damaged load are when many truckers feel left alone. We cannot promise how an insurer will rule, but we can help you gather clean photos, police reports, bills of lading and repair estimates so your claim is complete from the start. Being organized early tends to make the whole process calmer.
- License
- Licensed for property and casualty insurance
What Moves Your Premium
Truck insurance is priced on risk, and several pieces of your operation feed into it. Knowing those pieces helps you see why two quotes can look so different. We go over each one with you so nothing in the number feels like a mystery.
We put your quote together after we know your drivers, units, cargo and radius. You get it by phone with each coverage piece explained so you can compare fairly.
- Time under your authority
- A brand-new MC authority has no track record yet, so carriers price that unknown. Premiums often ease as you build clean years.
- Driver records and experience
- Years with a CDL, violations and accidents on each driver's record weigh heavily. One driver with recent tickets can change the cost for the whole policy.
- What you haul and how far
- Local dump work, regional hotshot loads and long-haul freight carry different risks. High-value or theft-prone cargo raises cargo coverage costs.
- Truck and trailer values
- Physical damage is priced on the stated value of each unit. Your deductible choice also shifts the premium up or down.
- Loss history
- Past losses show up on your loss runs, and underwriters read them closely. A clean history is one of the strongest things you can bring to a quote.
- Limits and add-ons
- Higher liability limits required by certain shippers, plus trailer interchange or non-trucking liability, each add to the total.
How Getting Covered Works
Most of this happens in one or two conversations. Here is what to expect.
- 1
Tell us about your operation
Call us and share your DOT number, MC authority status, the trucks you run and what you haul. If you are still applying for authority, that is fine too.
- 2
Gather the details
We ask for VINs, driver licenses and loss runs from any prior carrier. Having these ready keeps the quote accurate.
- 3
Review your quote together
We go through limits, deductibles and exclusions in plain words, by phone, video or at our office. You decide what fits your budget and your contracts.
- 4
Policy, filings and certificates
Once you choose, we help get coverage bound, your filings submitted and certificates of insurance sent where they need to go.
- 5
Support after a loss
If a truck is damaged or a load is lost, call us. We help you document what happened, report it correctly and understand the claim steps ahead.
Questions Truckers Ask Us
Something not covered here? (770) 405-1970
What do I need to get a quote?
Have your DOT number and MC number if you have them, VINs for each truck and trailer, and driver license details for everyone who will drive. Loss runs from your last insurer help too. If you are missing something, call anyway and we will tell you what matters most.
Why is insurance so expensive for a new authority?
Insurers have no history to judge a new motor carrier by, so they price for the unknown. Driver experience, a clean record and a clear description of your loads still help. We explain each part of the quote so you see where the cost comes from.
What is the difference between primary liability and bobtail coverage?
Primary auto liability covers damage you cause to others while operating under your own authority. Non-trucking liability, often called bobtail, is for leased owner-operators when they drive for personal reasons outside the motor carrier's dispatch. The motor carrier's policy usually handles liability while you are under dispatch.
Do you help with federal and state filings?
Yes. We help get the required filings submitted with your coverage so your authority can stay active. We also send certificates of insurance to brokers and shippers who request them.
What should I do right after an accident or cargo loss?
Make sure everyone is safe and contact the police if needed. Then take photos of every vehicle, the scene, the load and any seal numbers, and keep the bill of lading and driver logs. Call us so we can help you report it to the insurer and understand what comes next.
Will you decide whether my claim is paid?
No. The insurance company and its adjuster make the coverage decision under your policy. Our part is helping you document the loss well, explaining your policy language and keeping you informed along the way.
Does cargo coverage protect every load?
Not always. Many cargo policies exclude certain commodities or situations, such as unattended vehicles or refrigeration failure. We review those limits with you before you haul so there are no surprises.
Do I have to come to your office?
No. Many of our customers handle everything by phone or video. You are always welcome at our office if you would rather talk face to face.
Why Truckers Work With Us
A policy only proves its worth on a bad day. We spend time up front so you know what you bought, and we stay in the picture when you have to use it.
- A licensed agency
- We hold a license for property and casualty insurance. That means we can explain coverage, place policies and walk you through what your contract actually says.
- We read the exclusions with you
- Cargo forms often leave out certain commodities, unattended trucks or reefer breakdown. We point those lines out before you sign, not after a load goes bad.
- Help after a loss, without big promises
- After a wreck or cargo loss, we tell you what photos to take, which documents to save and who to report to. The insurance company's adjuster makes the coverage decision, and we will never tell you otherwise.
- Filings and certificates kept straight
- We help get your federal and state filings submitted and send certificates of insurance to shippers and brokers who ask for them. Fewer stalled loads waiting on paperwork.
- Meet the way that suits your schedule
- Sit down at our office, or handle it by phone or video between loads. Your truck stays on the road either way.
Let's Look at Your Coverage Together
Tell us how your operation runs and we will explain your options in plain terms. If you already have a policy, we can read it with you and point out any gaps.